Related News
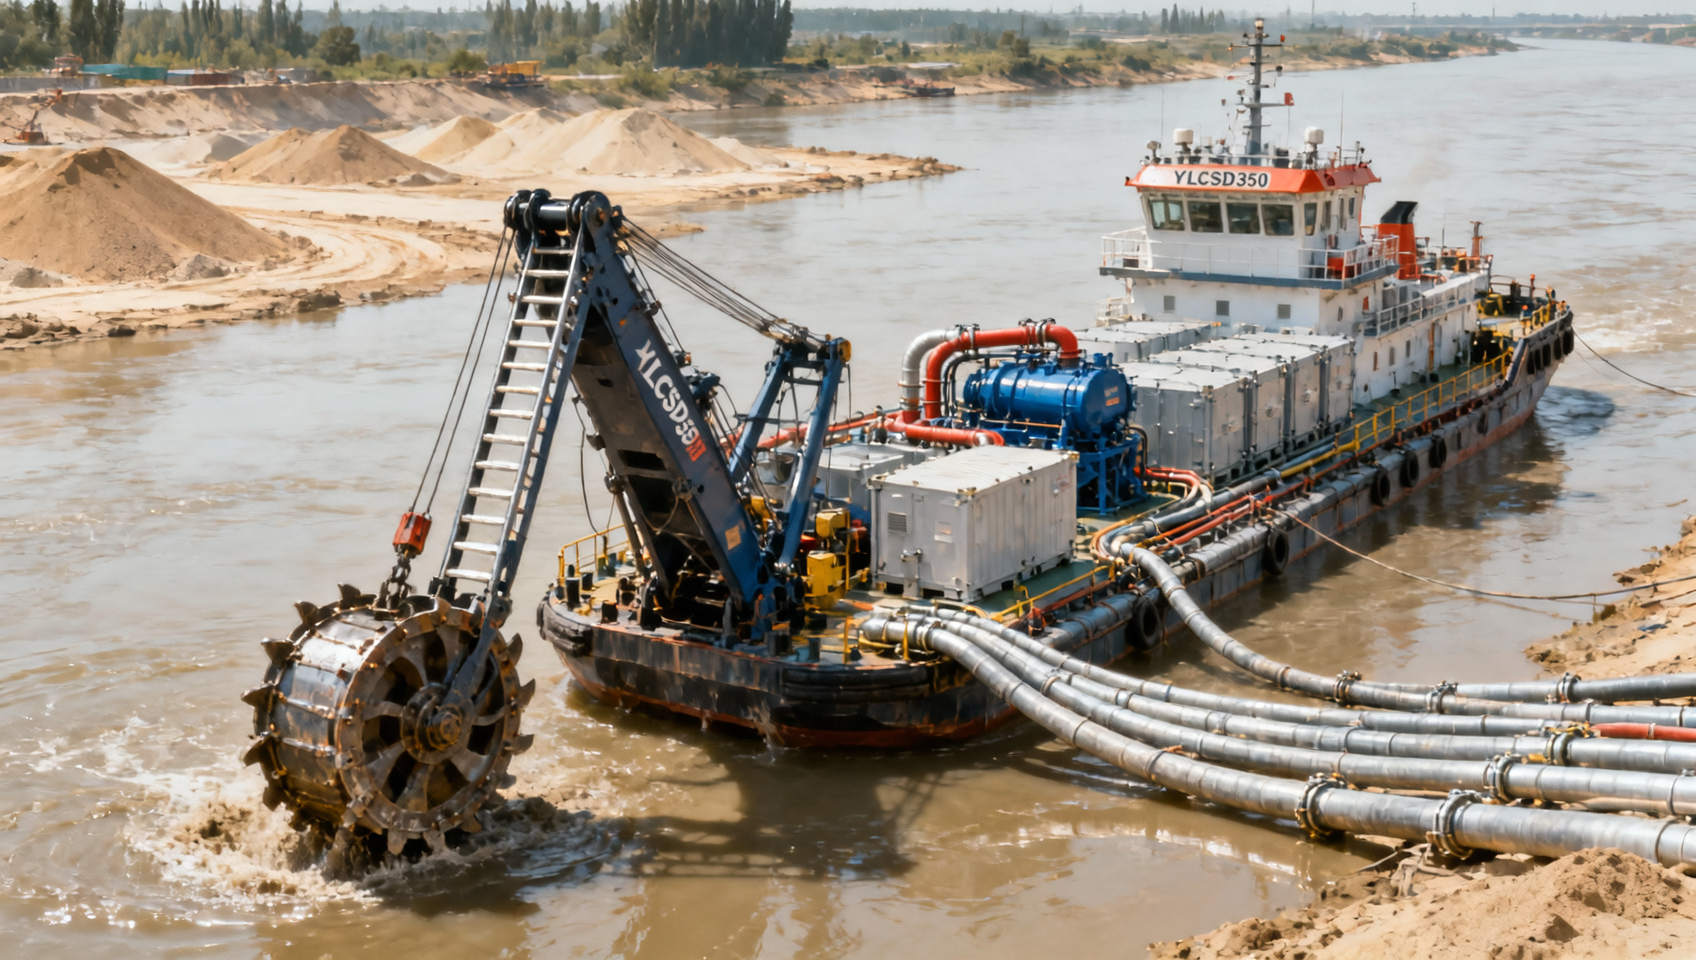
 What to Check Before Sourcing a YLCSD350 Cutter Suction Dredger for ProjectsAug 24, 2026
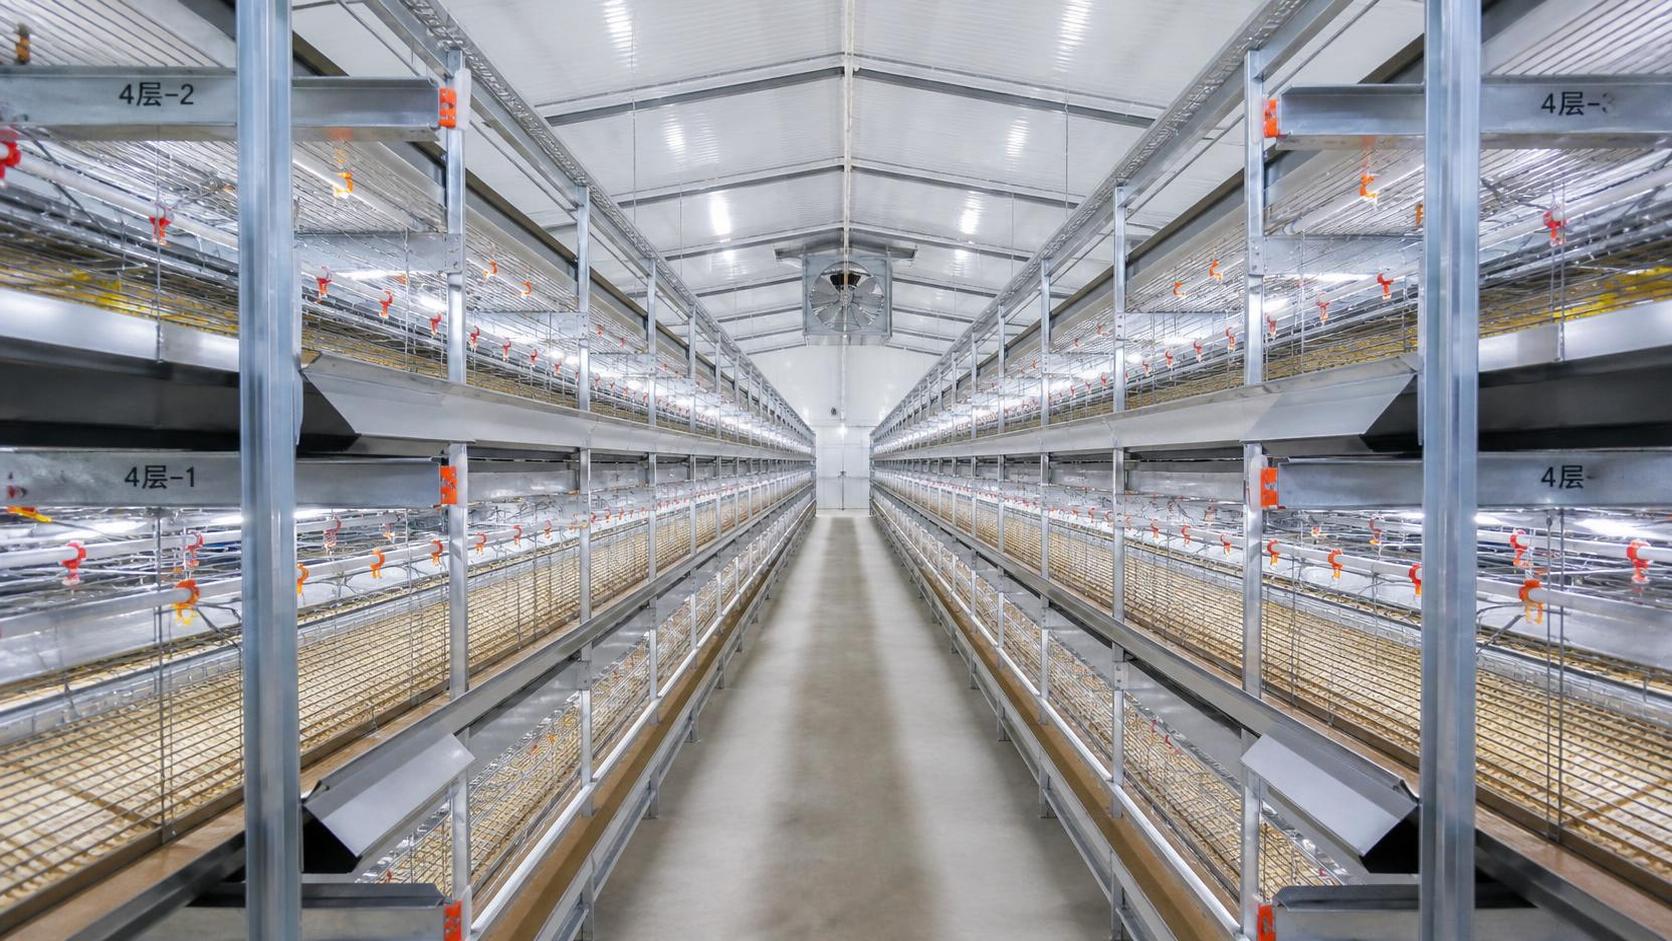
 Battery Cage System of Poultry Farming: What Determines Layer CapacityAug 21, 2026
- China’s Lithium Battery Chain Sees Strong Q2; Overseas Storage Orders LandAug 16, 2026
- China Expands Cross-Border Cash Pooling for Multinationals NationwideAug 15, 2026
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.
Related News
Supply chain cost reduction initiatives that worsen supplier collaboration in steel & metals




While supply chain cost reduction remains a top priority for automotive manufacturing solutions and heavy industry stakeholders, many well-intentioned initiatives—such as aggressive procurement optimization, automated manufacturing systems rollouts, or unsustainable sourcing mandates—unintentionally erode trust and transparency with steel & metals suppliers. This tension undermines procurement efficiency, weakens supplier collaboration, and contradicts sustainable manufacturing practices. Drawing on global trade report insights and real-world cases from manufacturing outsourcing companies and industrial supply wholesale networks, this analysis reveals how misaligned cost-cutting tactics disrupt long-term resilience—especially in capital-intensive sectors like heavy industry construction and machinery parts supplier ecosystems.
The Hidden Cost of Short-Term Procurement Leverage
In steel & metals procurement, cost pressure often manifests as unilateral contract renegotiations, compressed payment terms (e.g., net-30 to net-15), and mandatory volume rebates exceeding 8–12% annually. While these moves yield immediate P&L improvements, they trigger measurable downstream effects: supplier working capital strain increases by 22–35%, lead time variability rises by 40%, and technical support responsiveness drops by over 50% within six months.
A 2023 benchmark across 47 Tier-1 machinery OEMs showed that 68% applied annual price reductions without co-developing cost-out roadmaps with suppliers. Of those, 73% reported ≥2 major quality deviations per quarter—linked directly to supplier-driven material substitutions or process shortcuts. These are not isolated incidents but systemic outcomes of transactional, rather than relational, procurement governance.
Procurement teams frequently overlook the fact that steel producers and alloy fabricators operate on thin margins—typically 4–7% EBITDA—and face volatile input costs (scrap, ferro-alloys, energy). When buyers impose rigid cost targets without sharing visibility into demand forecasts or engineering change timelines, suppliers respond defensively—not collaboratively.
This table underscores a critical insight: cost levers that ignore supplier operational realities degrade information symmetry—the foundation of responsive, resilient supply chains. The most effective procurement functions treat steel & metals partners as extended engineering and planning resources—not just cost centers.
Automation Without Alignment: How Digital Rollouts Backfire
ERP and e-procurement platform deployments often assume standardization across supplier tiers. Yet in heavy industry, steel mills, foundries, and precision forging shops vary widely in digital maturity: only 39% of Tier-2 metal suppliers have API-ready MES systems, while 64% still rely on email/fax-based PO acknowledgments and shipment updates.
Forcing all suppliers onto a single procurement portal—without phased onboarding, training support, or legacy integration—results in manual workarounds. Field audits at 12 industrial equipment manufacturers revealed an average of 5.7 redundant data entry points per supplier transaction when automation is mismatched to capability.
Worse, automated RFQ scoring algorithms often prioritize lowest landed cost over total cost of ownership (TCO), omitting factors like metallurgical traceability compliance (ASTM A751, EN 10204 3.1), heat lot coordination for large structural components, or local inspection readiness—all critical in machinery and infrastructure projects where rework delays average 17–23 days.
Three High-Risk Automation Patterns
- “One-Size Portal” Mandates: Requiring ISO-certified documentation uploads within 48 hours—despite 42% of small-to-midsize mills lacking document management systems.
- Auto-Rejection Rules: Flagging orders with minor spec variances (e.g., ±0.3mm tolerance vs. ±0.2mm) without human review, triggering 28% more supplier dispute cases.
- Forecast Blindness: Feeding ERP-driven demand signals into supplier portals without validating against actual project milestone gates—causing 31% inventory misalignment in hot-rolled plate procurement.
Sourcing Mandates That Undermine Material Integrity
Sustainability-linked sourcing policies—while well-intentioned—often lack technical nuance. For example, mandating “100% recycled content” for structural weldments ignores ASTM A615/A615M requirements for deoxidation control and tensile uniformity. In practice, 14% of such mandates forced suppliers to use non-certified scrap blends, resulting in 3.2× higher rejection rates during third-party NDT inspections.
Similarly, geographic diversification mandates—e.g., “no single source >30% of billet volume”—ignore metallurgical consistency needs. A European OEM’s attempt to split orders across four EU mills led to inconsistent grain structure in forged crankshafts, increasing fatigue failure risk by an estimated 22% (per FEA modeling validated by TÜV SÜD).
These gaps reveal a core truth: sourcing policy must be calibrated to metallurgical and process realities—not just compliance checklists. Effective mandates embed technical guardrails, pre-qualify alternate routes, and co-develop transition roadmaps with suppliers.
Building Resilient Collaboration: Actionable Alternatives
Shift from cost negotiation to value co-creation. Pilot joint cost-out workshops with top 5 steel & metals suppliers—focusing on shared KPIs: scrap yield improvement (target: +4.5%), energy intensity reduction (target: −7% per tonne), and first-pass yield (target: ≥94%). Allocate 30% of realized savings to supplier innovation funds.
Implement tiered digital engagement: offer API integration for Tier-1 mills, cloud-based portal access for midsize forgers, and dedicated procurement coordinators for smaller specialty heat treaters. Track adoption via quarterly supplier digital maturity scores—not binary “on/off” status.
Adopt dynamic sourcing rules: allow up to 15% allocation flexibility per heat lot based on real-time mill capability dashboards (e.g., rolling mill availability, ladle furnace uptime). This preserves metallurgical integrity while enabling responsiveness.
Five Supplier Collaboration Uplift Actions
- Co-develop multi-year pricing frameworks indexed to LME/CRU indices + fixed conversion premiums (reviewed quarterly).
- Share 12-month rolling demand forecasts with granular project-phase tagging (e.g., “prototype,” “pre-series,” “volume ramp”).
- Establish joint metallurgical review boards with rotating supplier representation (minimum 2 meetings/year).
- Integrate supplier quality data into internal PPAP gate reviews—treating supplier SPC charts as primary evidence.
- Launch a supplier capability registry mapping heat treatment certifications, NDT coverage, and alloy-specific process limits.
Conclusion: From Transactional Savings to Structural Resilience
Cost reduction in steel & metals supply chains cannot be decoupled from technical partnership, process transparency, and mutual risk mitigation. Initiatives that bypass supplier capability constraints—or ignore metallurgical, regulatory, and operational interdependencies—generate false savings. Real resilience emerges not from squeezing margins, but from aligning incentives, sharing data intelligently, and treating suppliers as co-engineers of performance.
For procurement decision-makers and enterprise strategists, the path forward lies in replacing rigid cost mandates with adaptive, capability-aware collaboration models. This requires cross-functional alignment between procurement, engineering, quality, and sustainability teams—and investment in shared tools, metrics, and governance rhythms.
If your organization is evaluating supplier collaboration frameworks, digital integration roadmaps, or metallurgically grounded sourcing policies, contact our heavy industry supply chain advisory team for a no-cost diagnostic assessment aligned to your specific steel & metals ecosystem.