Related News
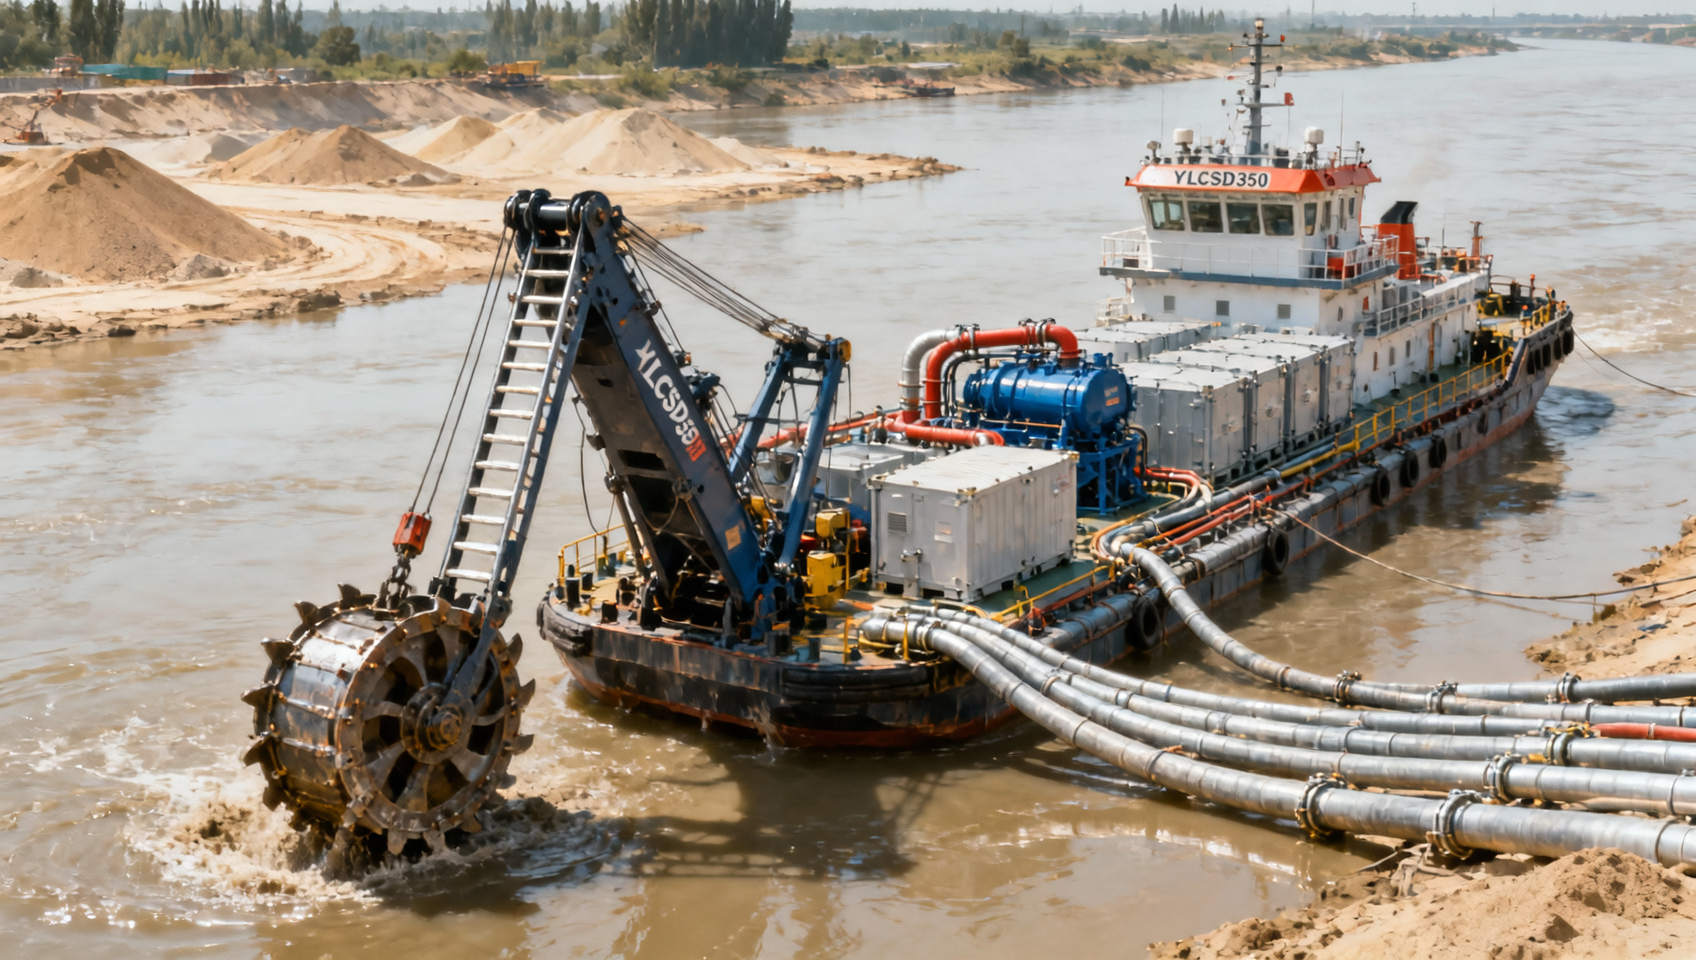
 What to Check Before Sourcing a YLCSD350 Cutter Suction Dredger for ProjectsAug 24, 2026
 Battery Cage System of Poultry Farming: What Determines Layer CapacityAug 21, 2026
- China’s Lithium Battery Chain Sees Strong Q2; Overseas Storage Orders LandAug 16, 2026
- China Expands Cross-Border Cash Pooling for Multinationals NationwideAug 15, 2026
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.
Related News
Construction equipment market growth stalled in India — not by policy, but by financing access





India’s construction equipment market growth has stalled—not due to policy headwinds, but because of persistent financing gaps. For procurement decision-makers and heavy equipment manufacturing stakeholders, this signals urgent need for actionable insights on heavy machinery market updates, construction equipment market dynamics, and linked mining & energy industry news. As excavator industry news and mineral price trends (e.g., iron ore market, bauxite exports) continue influencing capex decisions, understanding cross-sector linkages—from refining industry news to petrochemical price trends—is critical. Stay ahead with timely, professional intelligence tailored for enterprise leaders, operators, and global trade participants.
Why Financing—Not Policy—Is the Real Bottleneck
While India’s infrastructure pipeline remains robust—with over ₹11.2 lakh crore allocated to roads, railways, and urban development in FY2024–25—the construction equipment (CE) market grew just 2.3% YoY in Q1 2024, down from 9.7% in Q1 2023. This deceleration isn’t tied to regulatory shifts or import restrictions; instead, it reflects a structural constraint: only 38% of mid-sized contractors and equipment rental firms secure bank loans within 21 days of application, per RBI’s 2024 SME Lending Survey.
Equipment finance penetration stands at 52% for excavators and 41% for wheel loaders—well below the 76% average in Southeast Asia. The gap is most acute for Tier-2 and Tier-3 OEMs, where working capital cycles stretch beyond 90 days, delaying production ramp-ups and spare parts availability. Procurement teams report that 67% of delayed project starts trace back to equipment acquisition delays—not site readiness or approvals.
This financing shortfall cascades across the value chain: mining operators defer fleet upgrades despite rising iron ore demand (up 14% YoY), while energy infrastructure developers delay crawler crane deployments for solar park civil works—even as EPC timelines tighten to 18–24 months per 500 MW project.
How Equipment Buyers Are Adapting: 3 Real-World Strategies
Faced with constrained credit access, procurement professionals are shifting from transactional buying to structured asset deployment models. These approaches reduce upfront capex while maintaining operational control and service continuity.
- Rental-to-Own Programs: Offered by 12 major CE OEMs and 7 regional financiers, these require 15–20% down payment, followed by 36-month lease payments with buyout option at residual value (typically 12–18% of original price). Delivery lead time averages 14–21 days vs. 60+ days for full purchase.
- Pay-Per-Use Contracts: Deployed primarily for hydraulic excavators and motor graders on road projects. Billing is based on GPS-tracked operating hours (±3% accuracy), with maintenance bundled. Contract durations range from 3 to 12 months—ideal for seasonal or phased work.
- Consignment Stock Agreements: Used by large mining houses and port authorities. OEMs hold inventory at client sites under consignment; billing triggers only upon machine commissioning or monthly usage thresholds (e.g., ≥120 engine hours).
Each model reduces procurement cycle time by 40–65% and improves budget predictability—critical when raw material price volatility exceeds ±8% quarterly (as seen in bauxite and ferrochrome markets).
Procurement Decision Matrix: What to Evaluate Beyond Price
When financing options are limited, procurement teams must prioritize criteria that mitigate total cost of ownership (TCO) and ensure long-term deployability. The table below outlines five non-negotiable evaluation dimensions—and how they impact real-world ROI.
These parameters directly influence equipment uptime, operator retention, and compliance with India’s new Construction & Demolition Waste Management Rules—making them essential inputs for procurement scorecards, not optional add-ons.
What Heavy Industry Stakeholders Need Now
For information researchers, equipment operators, procurement leads, and enterprise decision-makers, the priority is no longer “what machines exist”—but “which configurations deliver predictable performance amid financing constraints.” That requires intelligence that connects equipment specs to real-world execution variables: monsoon season downtime risk, regional fuel sulfur content, local operator skill levels, and state-level GST treatment of leasing contracts.
Our platform delivers precisely this: cross-referenced data covering 23 CE OEMs, 14 mining & energy project pipelines, and live commodity price feeds (iron ore, bauxite, coking coal) updated every 4 hours. We map each equipment specification to its operational impact—e.g., how a 120 kW vs. 145 kW engine affects payload consistency on 8% gradients in Odisha’s iron ore belt.
Whether you’re evaluating excavator industry news for fleet renewal planning, benchmarking wheel loader TCO across 5 vendors, or validating whether your proposed financing structure complies with RBI’s latest NBFC guidelines for infrastructure assets—we provide the contextualized, source-verified intelligence needed to act—not just analyze.
Get Your Customized Intelligence Brief
Request an immediate assessment of your current procurement scenario—including equipment selection guidance, financing pathway analysis, and compliance alignment for upcoming tenders. Specify your focus: excavator specifications, loader payload optimization, mining fleet lifecycle cost modeling, or energy sector crane deployment timelines. Our analysts respond within 1 business day with actionable, vendor-agnostic recommendations.