Related News
 What to Check Before Sourcing a YLCSD350 Cutter Suction Dredger for ProjectsAug 24, 2026
 Battery Cage System of Poultry Farming: What Determines Layer CapacityAug 21, 2026
- China’s Lithium Battery Chain Sees Strong Q2; Overseas Storage Orders LandAug 16, 2026
- China Expands Cross-Border Cash Pooling for Multinationals NationwideAug 15, 2026
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.
Agri Machinery Industry Overview: Key Equipment Types and What Drives Demand





Why is the agri machinery industry getting so much attention now?
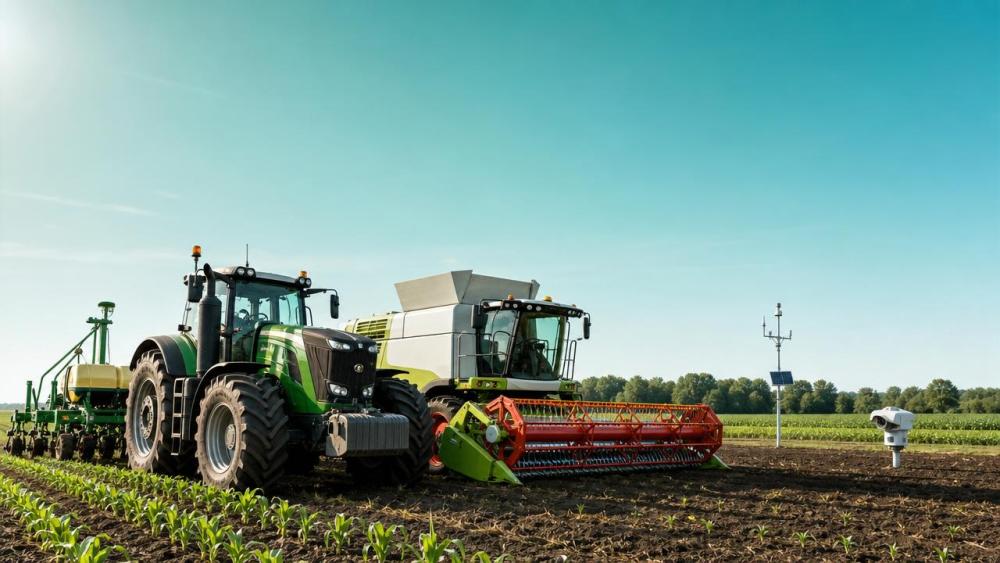
The agri machinery industry sits at the intersection of food production, industrial equipment, energy costs, and global trade. That is why attention has broadened far beyond farming alone.
Rising food demand is one driver, but not the only one. Labor shortages, climate pressure, and tighter margins are pushing operators to seek more output from each hectare.
In practical terms, machinery now matters as a productivity tool, a cost-control tool, and a data source. This shift changes how the agri machinery industry is evaluated.
It also explains why heavy industry information platforms track this sector closely. Steel prices, engine standards, hydraulic components, electronics supply, and export rules all influence machinery costs and delivery cycles.
Another reason is industrial upgrading. Smart manufacturing, automation, and emission reduction are no longer side topics. They now shape equipment design, sourcing choices, and after-sales planning.
So when people search for an agri machinery industry overview, they usually want more than a product list. They want to know what equipment matters, what demand signals are real, and what risks deserve attention.
Which equipment types define the agri machinery industry today?
The agri machinery industry covers a wide range of machines, but a few categories shape most investment discussions. These categories also influence upstream parts demand and downstream service needs.
Tractors remain the backbone
Tractors are still the most recognizable entry point. They support tillage, transport, spraying, seeding, and loader work through attachments and power take-off systems.
Demand often depends on horsepower segments. Smaller units fit fragmented land and mixed-use work. Larger models match broadacre farming and higher seasonal intensity.
Harvesters influence seasonal efficiency
Combines and forage harvesters matter because harvest windows are tight. When labor is limited or weather is unstable, harvesting capacity directly affects crop quality and loss rates.
This is why the agri machinery industry often sees strong attention on harvest equipment during periods of rising grain prices or changing crop structures.
Planting and crop care equipment are becoming more precise
Seed drills, planters, sprayers, and spreaders are moving toward variable-rate and section-control functions. That reduces overlap, saves inputs, and improves field consistency.
In actual use, the value is not only higher precision. It is also better recordkeeping for compliance, cost analysis, and yield comparison.
Precision farming systems are no longer optional extras
Guidance systems, telematics, sensors, and farm software increasingly shape machinery decisions. In many cases, hardware and data capability are now purchased together.
That changes the agri machinery industry from a purely mechanical market into a combined equipment-and-information market.
What actually drives demand in the agri machinery industry?
Demand is rarely driven by one factor. More often, it comes from a mix of crop economics, financing conditions, policy shifts, and replacement cycles.
A useful way to read the market is to separate short-term triggers from structural drivers. That helps avoid overreacting to one season or one regional headline.
Policy and regulation also deserve close attention. Import duties, local content rules, carbon frameworks, and safety standards can alter competitiveness faster than many buyers expect.
This is where industry news, regulatory tracking, and price monitoring become useful. They help interpret whether demand is broad-based, temporary, or concentrated in one equipment segment.
How do you compare machinery categories without oversimplifying the choice?
A common mistake is comparing equipment only by purchase price. The better approach is to compare fit, utilization rate, service support, and expected productivity under local conditions.
For example, a lower-cost tractor may look attractive at first. But weak parts availability or limited hydraulic performance can create higher costs during peak field periods.
The same applies to precision systems. A feature-rich platform is useful only if connectivity, operator training, and software compatibility are already in place.
- Match horsepower, working width, and throughput to actual field scale.
- Check engine compliance and local regulatory acceptance before import decisions.
- Review spare parts lead times, especially for sensors, tires, and hydraulic components.
- Estimate downtime risk during planting and harvest, not only annual running hours.
- Confirm whether data systems can integrate with existing software and fleet tools.
In the agri machinery industry, comparison is really about total operating fit. That includes machine capability, service ecosystem, finance terms, and residual value.
Where do buyers and market watchers misread the agri machinery industry?
One misreading is assuming every demand increase signals a long-term boom. Sometimes demand rises because replacement was delayed, not because the market has fundamentally expanded.
Another is focusing only on headline unit sales. A healthier reading also looks at order backlogs, dealer inventory, financing stress, and export destination changes.
Supply chains create their own distortion. Steel, semiconductors, castings, and transmissions can affect delivery times. When supply normalizes, reported growth may cool even if underlying demand remains stable.
There is also a technology trap. Not every digital feature creates real value. In practical evaluation, reliable automation with measurable field savings often beats a long feature list.
Corporate activity deserves attention too. Capacity expansion, acquisitions, production line upgrades, and international partnerships can change pricing power and regional competition across the agri machinery industry.
What should be watched next if you want a clearer view of market direction?
The next phase of the agri machinery industry will likely be shaped by three connected themes: smarter equipment, stricter compliance, and more selective capital spending.
Smarter equipment means more factory-installed telematics, better guidance accuracy, and stronger links between machinery and agronomic data. This trend supports both productivity and traceability.
Stricter compliance will affect engines, emissions, safety, and sometimes trade documentation. That can influence sourcing strategy, refurbishment decisions, and aftermarket planning.
Selective capital spending means buyers are likely to prioritize machines with clear return profiles. High-use assets and upgradeable platforms may gain preference over broad fleet expansion.
For ongoing analysis, it helps to monitor several signals together rather than in isolation.
- Crop prices versus machinery financing costs.
- Regional subsidy adjustments and environmental rules.
- Raw material trends affecting steel-intensive equipment.
- Export demand, tariff changes, and supply chain relocation.
- Manufacturer project updates and technology rollout speed.
In that sense, the agri machinery industry is best understood through connected industrial signals. Equipment demand, policy shifts, technology upgrades, and trade flows now move together more often.
A sensible next step is to map equipment categories against real use cases, service coverage, cost cycles, and compliance requirements. That creates a more reliable basis for comparison and follow-up decisions.
If the goal is better market judgment, keep tracking machinery news alongside metals, energy, logistics, and export developments. That wider context usually explains demand faster than unit sales alone.