Related News
 Are Carbon Fiber Composites Ready for Mass Use in Construction Equipment?Oct 08, 2026
- How to Verify an Industrial Supplier’s Delivery Track RecordOct 08, 2026
 What Should Buyers Do When a Key Supplier Raises Prices Mid-Contract?Oct 08, 2026
- How Do Trade Sanctions Affect Heavy-Industry Supply Chains?Oct 08, 2026
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.
Related News
Cement market updates hint at something unusual: price resilience amid falling clinker output




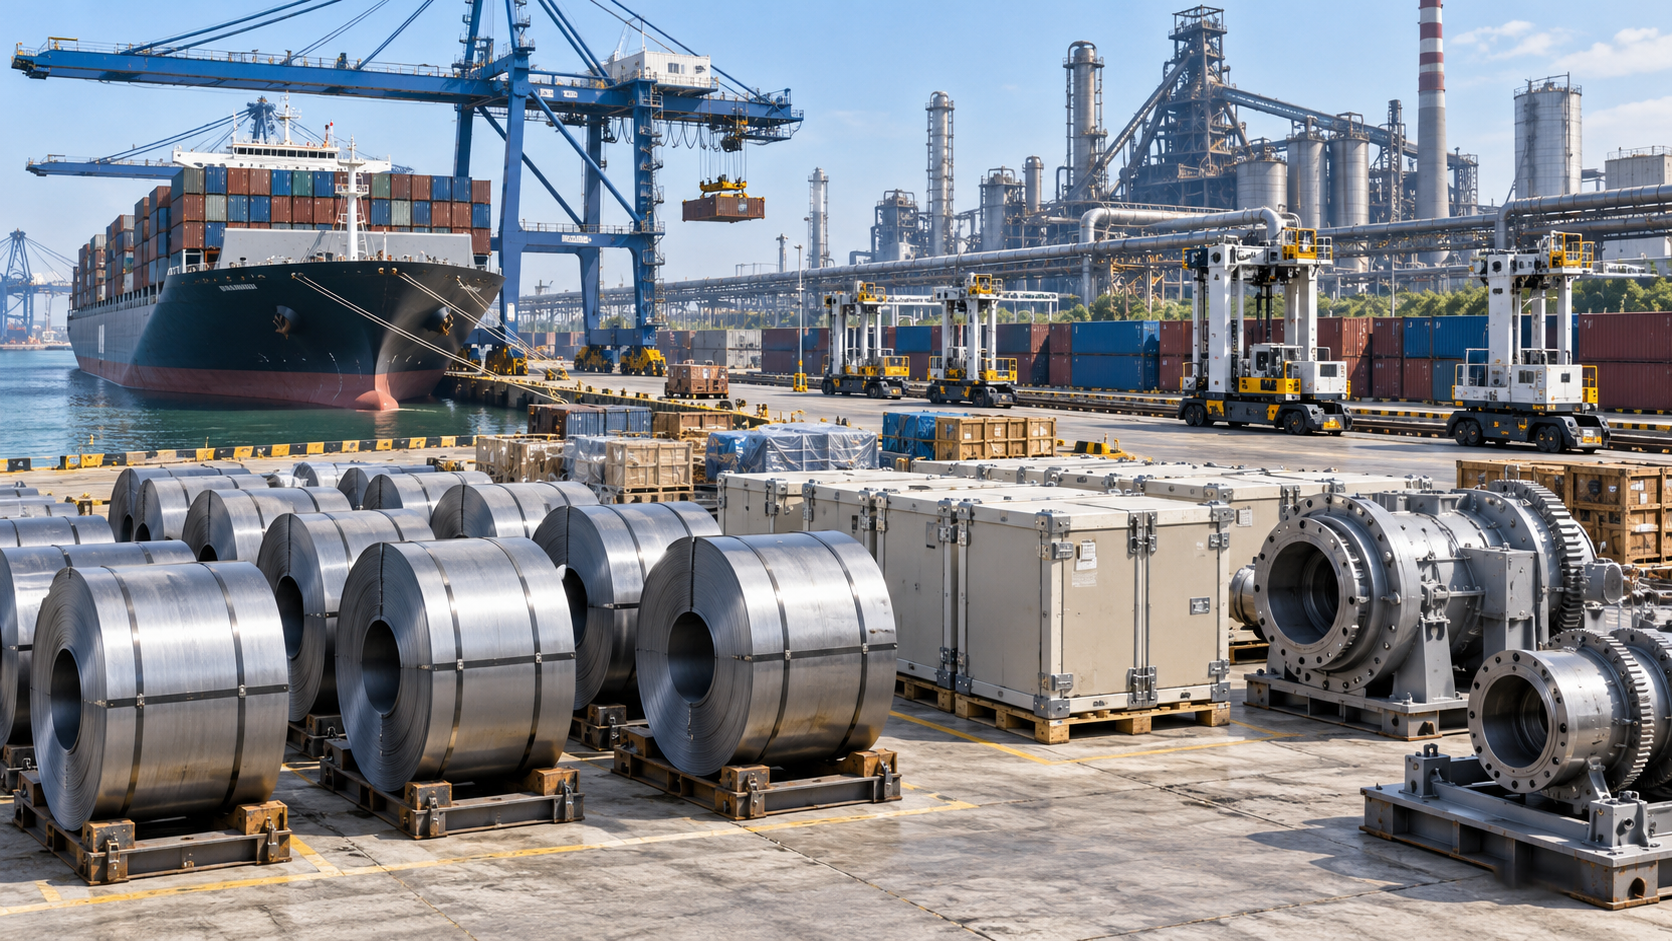
Cement market updates are defying conventional supply-demand logic: prices remain stubbornly resilient despite a notable drop in clinker output—a trend drawing urgent attention from procurement decision-makers and heavy industry news updates subscribers. As energy saving and emission reduction policy enforcement tightens across key producing regions, industrial environmental news and environmental equipment news point to structural shifts in production capacity. This anomaly intersects with broader power market updates, steel market updates, and mineral price trends—making it critical intelligence for information调研者, enterprise strategists, and global export trade policy analysts. Stay ahead with actionable insights rooted in real-time heavy machinery market updates and industrial export news.
Why Is Cement Pricing Defying Supply Constraints?
This counterintuitive trend stems not from demand surges, but from systemic bottlenecks in the downstream processing chain—particularly in grinding, blending, and dispatch infrastructure tied to cement manufacturing machinery. Clinker output fell by 8–12% YoY in Q2 across China’s Yangtze River Delta and Hebei provinces, per provincial industrial output bulletins—but cement ex-factory prices held within ±1.3% of Q1 averages.
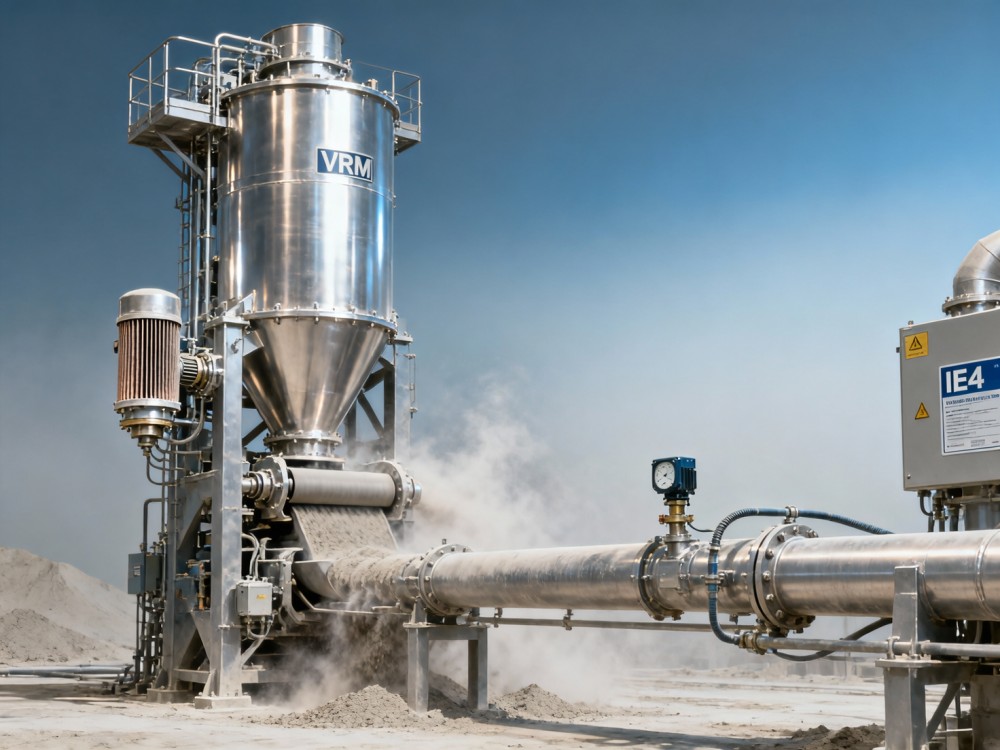
The root cause lies in constrained capacity utilization of vertical roller mills (VRMs) and ball mills—equipment whose maintenance cycles, spare part lead times (typically 6–10 weeks), and energy efficiency thresholds directly govern final product throughput. With over 65% of active VRMs operating beyond their recommended 8-year service life, unplanned downtime has risen by 22% since early 2024.
Meanwhile, regulatory tightening on dust suppression systems and NOx scrubbers has forced 14% of mid-tier plants to halt operations for retrofits lasting 3–5 weeks—further compressing effective grinding capacity without reducing clinker inventory levels.
How Procurement Teams Should Assess Grinding Equipment Risk
Procurement professionals must shift focus from clinker availability metrics to grinding line resilience indicators. Three operational KPIs now outweigh traditional cost-per-ton benchmarks:
- Mean time between failures (MTBF) for mill drive gearboxes — target ≥1,800 hours under continuous load
- Availability of certified replacement rollers and liners — verified stock within 200 km radius or ≤4-week air freight window
- Compatibility with modular dust control integration — requires API RP 14C or EN 14175 compliance documentation
These parameters directly impact your ability to maintain output during regional emission compliance windows. Plants with MTBF <1,200 hours face 3.2× higher risk of missing quarterly delivery commitments when clinker inventories dip below 10-day coverage.
Key Grinding Equipment Procurement Dimensions
This table reflects field-validated thresholds used by Tier-1 cement producers across Southeast Asia and Eastern Europe. Equipment falling short on any two dimensions increases total cost of ownership by 17–29% over a 5-year lifecycle—primarily due to unplanned shutdowns and regulatory penalties.
What’s Next for Heavy Machinery Suppliers in Cement Value Chains?
Manufacturers supplying grinding mills, classifiers, and pneumatic conveying systems must now offer integrated lifecycle support—not just hardware. Leading suppliers now bundle:
- Remote vibration monitoring with predictive maintenance alerts (response time <15 minutes for critical faults)
- Pre-certified liner kits compliant with local environmental agency requirements (e.g., China’s GB 4915-2023)
- On-site operator upskilling modules delivered in 3–4 hour sessions, aligned with ISO 55001 asset management standards
These services reduce average commissioning delays by 3.8 weeks and cut first-year spare parts ordering errors by 41%. For procurement teams, this means clearer TCO modeling and reduced reliance on third-party engineering consultants.
Upstream, clinker transport equipment providers are adapting too: bulk trailer fleets now integrate real-time payload sensors calibrated to ±0.25% accuracy—critical when clinker moisture content fluctuates above 0.8%, triggering automatic discharge hold protocols.
Why Partner With Our Platform for Cement Machinery Intelligence?
We deliver more than market headlines—we translate clinker output data, emissions regulation timelines, and grinding equipment performance benchmarks into procurement-ready action plans. Our platform provides:
- Live feed of 32+ regional cement plant maintenance calendars—updated weekly, with outage duration, scope, and OEM-part dependency flags
- Equipment specification crosswalks mapping legacy mill models (e.g., FLS OK 32/35) to current IE4-compliant replacements—including retrofit feasibility scoring
- Customized RFQ templates pre-loaded with compliance clauses for GB, EN, ASTM, and IS standards—reducing legal review cycles by 65%
Whether you’re validating a supplier’s MTBF claim, benchmarking liner wear rates across 5 vendors, or aligning mill upgrades with your plant’s 2025 carbon budget—our team provides direct access to heavy machinery engineers with 12+ years’ cement sector experience. Contact us today to request:
- A free grinding line resilience audit (includes 3 priority KPI recommendations)
- Regional compliance timeline dashboard for your top 3 sourcing locations
- Customized spare parts lead time forecast based on your current OEM contracts