Related News
 What to Check Before Sourcing a YLCSD350 Cutter Suction Dredger for ProjectsAug 24, 2026
 Battery Cage System of Poultry Farming: What Determines Layer CapacityAug 21, 2026
- China’s Lithium Battery Chain Sees Strong Q2; Overseas Storage Orders LandAug 16, 2026
- China Expands Cross-Border Cash Pooling for Multinationals NationwideAug 15, 2026
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.
Related News
EU Ends Duty Relief for Low-Value Parcels





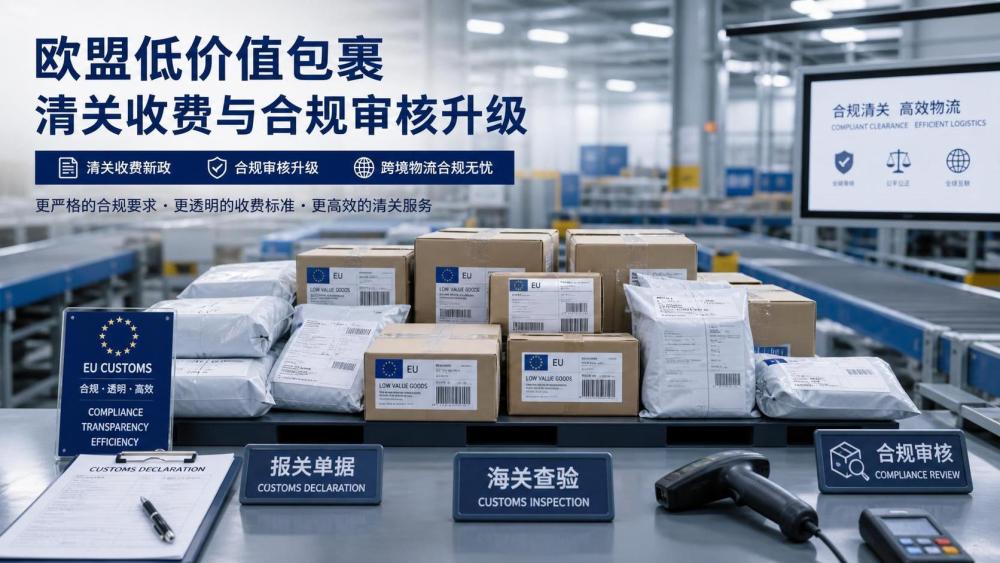
On July 1, 2026, the EU is set to remove the long-standing duty exemption for low-value cross-border parcels under EUR 150 and apply a fixed EUR 3 customs clearance charge to each directly shipped personal consumer item entering the bloc from abroad. With a transition period running until July 2028 and major cross-border platforms named as importers of record, this change is relevant not only to marketplaces but also to exporters, distributors, procurement teams, and supply chain service providers that rely on direct-to-consumer parcel flows into the EU.
What the rule change confirms from July 1
The confirmed change is that, from July 1, 2026, the EU will end the tariff exemption that had applied for more than a decade to parcels valued below EUR 150. For personal consumer goods shipped directly from outside the EU to individual buyers in the EU, a fixed EUR 3 customs clearance charge will apply per parcel.
The provided information also confirms that the transition period will continue until July 2028. In addition, platforms including Temu, SHEIN, and AliExpress are explicitly identified as the responsible import parties and are required to assume both duty payment and product compliance obligations.
Where the pressure is likely to appear first
Direct-to-EU parcel sellers will face a different cost base
From an industry perspective, businesses that depend on low-value direct mail shipments into the EU are likely to feel the effect first because the rule change directly alters the unit economics of parcel-by-parcel fulfillment. The main impact is likely to appear in pricing, margin control, order splitting practices, and SKU selection for lower-priced items. What deserves closer attention is whether supporting customs documentation, product compliance files, and shipment data are ready to match a more formal import responsibility structure.
Platforms and channel operators will need tighter compliance control
Because named platforms are identified as import responsibility holders, the impact is not limited to tax handling alone. Analysis shows that platform-side controls over product conformity, seller onboarding, listing review, and documentation retention are likely to become more important operational checkpoints. Businesses using marketplace channels should pay close attention to any changes in document submission requirements, product file readiness, and proof of compliance expected before goods are allowed into the sales flow.
Distributors and procurement teams may need to revisit product mix
For distributors, cross-border channel managers, and procurement teams, the rule change may affect which products remain practical for direct shipment into the EU. The most exposed business steps are likely to include landed-cost calculation, order planning, replenishment choices, and delivery promise management. Observably, companies should watch whether lower-ticket items, fast-turn listings, or compliance-sensitive categories require different sourcing or routing decisions under the new fee structure and importer liability framework.
Logistics and clearance service providers may see process adjustments
Supply chain service providers involved in parcel forwarding, customs handling, and delivery coordination may be affected through changes in declaration workflows, timing expectations, and document completeness standards. The key issue is less about a single fee and more about whether shipment data, importer responsibility allocation, and product compliance evidence are aligned well enough to avoid clearance friction or service delays.
What companies should review now
Check whether compliance files can support importer responsibility
Analysis shows that businesses should not treat the update as a pricing issue alone. Where platforms or channel operators are carrying import responsibility, product compliance materials, technical files, declarations, and traceability records may become more operationally significant. The current information does not provide detailed enforcement mechanics, so this is better understood as a point for immediate review rather than a confirmed final procedure.
Rework cost and SKU assumptions for direct-shipping models
Companies relying on direct parcel fulfillment into the EU should reassess whether current pricing, promotional structures, and low-value assortment strategies remain workable once each parcel carries a fixed customs clearance charge. The practical focus should be on shipment design, order structure, and category selection, especially where margins are already narrow.
Watch for evolving execution standards during the transition period
Because the transition runs until July 2028, businesses should continue monitoring how the rule is expressed in practice through customs handling, platform requirements, and compliance review expectations. What deserves closer attention is not only the headline measure itself, but also any later clarification on documentation standards, operational responsibility, and category-specific implementation.
Prepare for knock-on effects in delivery promises and after-sales handling
Observably, any change in customs responsibility and parcel treatment can influence clearance timing and customer-facing delivery commitments. Exporters, channel operators, and after-sales teams should therefore review how delays, returned goods, and quality traceability may need to be handled if import compliance checks become more central to parcel processing.
Why this looks like both a landed rule and an execution signal
Analysis shows that this development is more than a general policy discussion because it includes a start date, a fixed parcel charge, a transition window, and explicit importer responsibility for named platforms. At the same time, it is more appropriate to understand this as a rule that has formally landed while still requiring close observation of how enforcement standards, compliance expectations, and channel-level operating rules are applied in practice.
How the market is likely to read this change
From an industry perspective, the immediate significance of this update is that low-value direct shipping into the EU can no longer be evaluated mainly through product price and freight alone. The rule change points to a stricter link between customs cost, importer liability, and product compliance. It is more appropriate to understand this development as an active operating change with further execution details still worth tracking, rather than as a completed outcome with every practical question already settled.
Basis of this article and what still needs verification
This article is based on the user-provided news title, event date, and event summary. For developments of this type, relevant source categories commonly include official announcements, regulatory releases, customs or trade authority information, industry association updates, standards-related documents, and reporting by established professional media. A specific official source link was not provided in the input, so further verification remains necessary. Continued attention should be given to later policy detail, compliance interpretation, tender or commercial document changes, market feedback, and how companies implement the new requirements in practice.